
Truth, Trends, Takes. Truth, Trends, Takes.
  • Personal Finance
  • Tech
  • Entertainment
  • Health
  • Lifestyle
  • Education
  • Reviews
  • Abroad
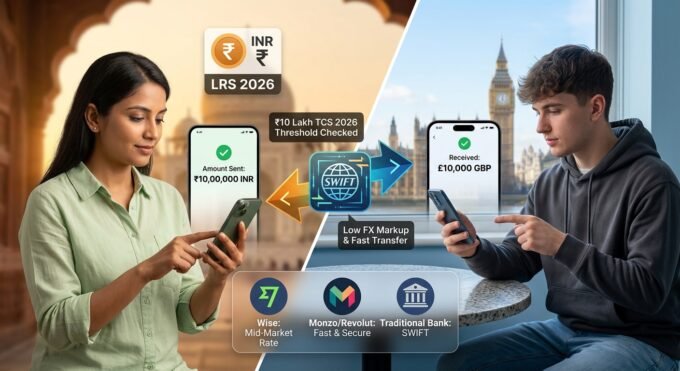
    This header image perfectly encapsulates the key elements of your blog post. It visually bridges India and the UK, explicitly referencing specific financial regulations like the 'LRS 2026' and '₹10 Lakh TCS Threshold' discussed in the text. I've also included logos and rate highlights for Wise, Monzo, Revolut, and traditional banks to directly align with your fee table and detailed breakdown.
    Abroad

    Wise vs Revolut vs Monzo vs Bank Transfer: India to UK (2026 Tested)

    Ansar Sk4 Mins read
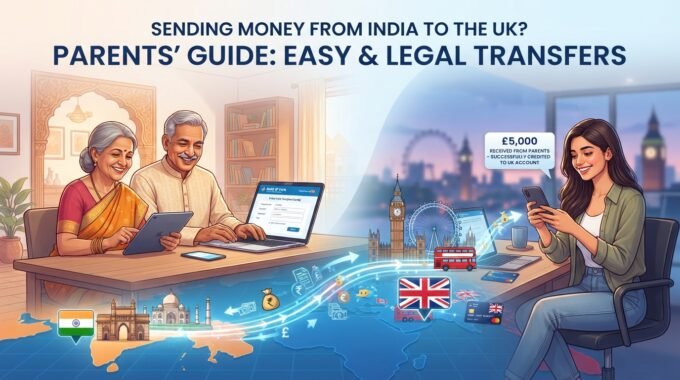
    This guide outlines the key steps and considerations for parents in India sending money to a UK bank account in 2026. Key Requirements & Limits (RBI LRS) Under the Reserve Bank of India's (RBI) Liberalised Remittance Scheme (LRS), resident individuals can remit up to $250,000 (approx. ₹2 Crores) per financial year for any permissible current or capital account transaction, including family maintenance. Tax Implications (TCS) A crucial change in recent years is the application of Tax Collected at Source (TCS) on remittances under the LRS: - Threshold: TCS applies if the total amount remitted by an individual in a financial year exceeds ₹7 Lakhs. - Rate (2026): The current TCS rate for most remittances (including for family maintenance) is 5%. Note: This TCS is not an additional tax but an advance tax credit. It can be claimed when filing your Income Tax Return (ITR). Documents Required To process the transaction, your parents will typically need to submit the following documents to their bank in India: 1. PAN Card: Mandatory for all LRS remittances. 2. Aadhaar Card: For identity and address verification. 3. Remittance Application Form (A2 Form): This form specifies the purpose of the remittance (in this case, family maintenance) and declares the source of funds. 4. Passport Copy (Beneficiary): A copy of your passport for identification of the recipient in the UK. 5. UK Bank Details: Your full name as per the account, IBAN (International Bank Account Number), and SWIFT/BIC code of your UK bank. Best Ways to Transfer Funds Safely Choosing the right method is essential to balance speed, cost, and exchange rates. 1. Bank Wire Transfer (SWIFT): - Reliable: Direct transfer from an Indian bank account to a UK bank account. - Considerations: Can be slower (2-5 business days) and often involves higher transfer fees, correspondent bank charges, and a less favorable exchange rate. 2. Online Money Transfer Services (e.g., Wise, Remitly, Xoom): - Cost-Effective: Often offer much better exchange rates than banks and lower, transparent transfer fees. - Fast: Many transfers are completed within the same day or even instantly. - Regulated: These platforms are fully authorized and regulated (e.g., by the FCA in the UK). 3. Foreign Exchange Cards (Multi-Currency Cards): - Your parents can load the card in Indian Rupees (INR) and you can withdraw Pounds (GBP) from ATMs in the UK. - Considerations: Exchange rates apply when loading the card, and ATM withdrawal fees may apply. Safety Tips - Always use regulated entities: Ensure the bank or money transfer service you choose is authorized by the RBI (in India) and the FCA (in the UK). - Beware of scams: Never share your banking passwords or OTPs with anyone, even if they claim to be from a transfer service. - Compare rates: Before making a transfer, compare the total cost (fees + exchange rate) offered by different providers to ensure you get the best value. Disclaimer: The information provided above is for general guidance based on regulations as of 2023/2024 and is subject to change. It is highly recommended to consult with your bank or a qualified financial advisor in India before making an international remittance. Infographic Placeholder: Visual Summary of the Steps [Placeholder: A clear infographic showing the process flow: 1. Parents (India) initiate request. 2. Bank verifies PAN/Aadhaar/A2 Form. 3. RBI LRS limit and TCS check. 4. Funds converted and sent via SWIFT/Wise. 5. Money received in UK Bank Account (2026 Guide). This visual element will be available in the final article.]
    Abroad

    How to Send Money from India to UK Bank Account (2026 Guide)

    Ansar Sk3 Mins read
    All/ Abroad/ Active/ Business/ Health/ Inspiration/ Sports/ Tech/ Uncategorized/
    This header image perfectly encapsulates the key elements of your blog post. It visually bridges India and the UK, explicitly referencing specific financial regulations like the 'LRS 2026' and '₹10 Lakh TCS Threshold' discussed in the text. I've also included logos and rate highlights for Wise, Monzo, Revolut, and traditional banks to directly align with your fee table and detailed breakdown.
    Abroad

    Wise vs Revolut vs Monzo vs Bank Transfer: India to UK (2026 Tested)

    Ansar Sk4 Mins read
    This guide outlines the key steps and considerations for parents in India sending money to a UK bank account in 2026. Key Requirements & Limits (RBI LRS) Under the Reserve Bank of India's (RBI) Liberalised Remittance Scheme (LRS), resident individuals can remit up to $250,000 (approx. ₹2 Crores) per financial year for any permissible current or capital account transaction, including family maintenance. Tax Implications (TCS) A crucial change in recent years is the application of Tax Collected at Source (TCS) on remittances under the LRS: - Threshold: TCS applies if the total amount remitted by an individual in a financial year exceeds ₹7 Lakhs. - Rate (2026): The current TCS rate for most remittances (including for family maintenance) is 5%. Note: This TCS is not an additional tax but an advance tax credit. It can be claimed when filing your Income Tax Return (ITR). Documents Required To process the transaction, your parents will typically need to submit the following documents to their bank in India: 1. PAN Card: Mandatory for all LRS remittances. 2. Aadhaar Card: For identity and address verification. 3. Remittance Application Form (A2 Form): This form specifies the purpose of the remittance (in this case, family maintenance) and declares the source of funds. 4. Passport Copy (Beneficiary): A copy of your passport for identification of the recipient in the UK. 5. UK Bank Details: Your full name as per the account, IBAN (International Bank Account Number), and SWIFT/BIC code of your UK bank. Best Ways to Transfer Funds Safely Choosing the right method is essential to balance speed, cost, and exchange rates. 1. Bank Wire Transfer (SWIFT): - Reliable: Direct transfer from an Indian bank account to a UK bank account. - Considerations: Can be slower (2-5 business days) and often involves higher transfer fees, correspondent bank charges, and a less favorable exchange rate. 2. Online Money Transfer Services (e.g., Wise, Remitly, Xoom): - Cost-Effective: Often offer much better exchange rates than banks and lower, transparent transfer fees. - Fast: Many transfers are completed within the same day or even instantly. - Regulated: These platforms are fully authorized and regulated (e.g., by the FCA in the UK). 3. Foreign Exchange Cards (Multi-Currency Cards): - Your parents can load the card in Indian Rupees (INR) and you can withdraw Pounds (GBP) from ATMs in the UK. - Considerations: Exchange rates apply when loading the card, and ATM withdrawal fees may apply. Safety Tips - Always use regulated entities: Ensure the bank or money transfer service you choose is authorized by the RBI (in India) and the FCA (in the UK). - Beware of scams: Never share your banking passwords or OTPs with anyone, even if they claim to be from a transfer service. - Compare rates: Before making a transfer, compare the total cost (fees + exchange rate) offered by different providers to ensure you get the best value. Disclaimer: The information provided above is for general guidance based on regulations as of 2023/2024 and is subject to change. It is highly recommended to consult with your bank or a qualified financial advisor in India before making an international remittance. Infographic Placeholder: Visual Summary of the Steps [Placeholder: A clear infographic showing the process flow: 1. Parents (India) initiate request. 2. Bank verifies PAN/Aadhaar/A2 Form. 3. RBI LRS limit and TCS check. 4. Funds converted and sent via SWIFT/Wise. 5. Money received in UK Bank Account (2026 Guide). This visual element will be available in the final article.]
    Abroad

    How to Send Money from India to UK Bank Account (2026 Guide)

    Ansar Sk3 Mins read
    Uncategorized

    Hello world!

    Ansar Sk1 Mins read
    Tech

    PS Plus Extra/Premium June 2024 Game Revealed, Will Be Part of Regular Lineup

    Ansar Sk2 Mins read
0

No products in the basket.

Home Uncategorized

Uncategorized

1 Articles
Uncategorized

Hello world!

Welcome to WordPress. This is your first post. Edit or delete it, then start writing!

Ansar Sk1 Mins read
  • Facebook 23k Likes
  • 93k Follows
  • Instagram 32k Follows
  • Pinterest 42k Pin
  • YouTube 100k Subscribers
  • Spotify 65k Followers

Explore more

Inspiration

The Books We Read Too Late And That You Should Read Now

Ansar Sk2 Mins read
Active

The Unexpected Power of Seeing Yourself as a Villain

2 Mins read
Health

7 food myths dietitians wish people would stop believing

2 Mins read
Active

Outdoor Photo Shooting With clean and Beautiful

2 Mins read
SwipeNxt
  • Facebook 23k Likes
  • 93k Follows
  • Instagram 32k Follows
  • Pinterest 42k Pin
  • YouTube 100k Subscribers
  • Spotify 65k Followers

Get to Know Us

  • Personal Finance
  • Tech
  • Entertainment
  • Health
  • Lifestyle
  • Education
  • Reviews
  • Abroad

Keep in touch

Subscribe to our newsletter to get our newest articles instantly!

    © Copyright 2025 SwipeNxt. All Rights Reserved.

    Our website uses cookies to improve your experience. Learn more about cookie policy
    Accept
    Truth, Trends, Takes. Truth, Trends, Takes.
    • Home
    • Abroad
    • Business
    • Tech
    • Health
    • Inspiration
    • Sports
    • Contact US

    Weekly update

    Sports

    The Unorthodox Solution to the World’s Migration Woes

    2 Mins read
    Inspiration

    The Books We Read Too Late And That You Should Read Now

    2 Mins read
    Active

    The Unexpected Power of Seeing Yourself as a Villain

    2 Mins read

    Weekly Newsletter

    Excepteur sint occaecat cupidatat non proident

      © Copyright 2025 SwipeNxt. All Rights Reserved.